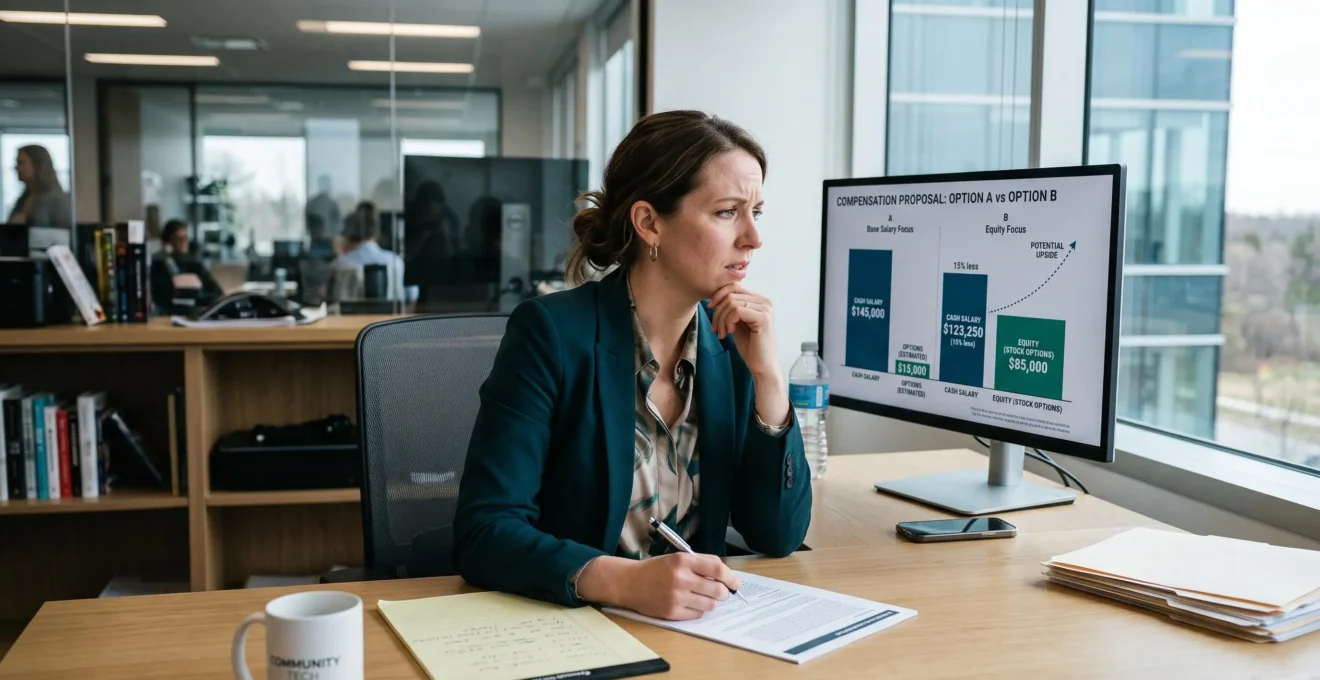
A Canadian startup offering 15% less salary in exchange for equity is asking you to make two decisions at once: whether the job is worth taking and whether the financial risk is worth accepting. Those decisions should not depend on the same assumptions.
Suppose your current salary is $120,000 CAD and a Toronto startup offers $102,000 CAD plus stock options. The immediate difference is $18,000 annually before tax. Over four years, that represents $72,000 in forgone gross salary, assuming neither salary changes. The equity could eventually exceed that amount, but it could also produce no financial return.
For professionals in Toronto, Montreal, Vancouver or remote roles, the calculation also includes career development, company funding, taxes, job security, benefits and commuting time. A startup may provide exceptional experience without providing an exceptional financial outcome.
The useful question is not whether startup equity is exciting. It is whether the full offer improves your career and financial position under outcomes you can realistically tolerate.
Should you accept a lower salary for Canadian startup equity?
- Value equity conservatively: treat stock options as uncertain upside, not guaranteed compensation replacing the 15% salary reduction.
- Investigate the business: review runway, financing, option terms, vesting, exercise costs and employee turnover before committing.
- Compare the complete package: salary, pension, benefits, learning opportunities, working hours and commuting costs can matter more than the headline equity percentage.
- Why Does Startup Equity in Canada Often Feel Less Valuable Than People Expect?
- How to Evaluate a Canadian Startup Offer in 30 Minutes Using 7 Red Flags and 7 Green Flags?
- Which Is the Better Move in Canada: A Startup Role or a Government Job for Long-Term Stability?
- The Equity Paperwork Mistake That Can Surprise Canadian Startup Employees at Tax Time
- When Is the Best Time to Join a Canadian Startup: Pre-Seed, Series A, or Later?
- Why Do Jobs Cluster in the Toronto–Waterloo Corridor Instead of Spreading Across Ontario?
- Why Do Canadian Startups Raise Smaller Rounds Even With Strong Traction?
- Is the Toronto–Waterloo Corridor Worth the Commute if It Adds 8 Hours a Week?
Why Does Startup Equity in Canada Often Feel Less Valuable Than People Expect?
Canadian startup equity often feels less valuable than expected because the number in an offer letter represents potential ownership, not spendable money. Private shares are difficult to sell, option exercises may require cash, future financing can dilute ownership, and a profitable exit is never guaranteed. The financial outcome depends on the specific rights attached to the equity.
Employees sometimes interpret a company’s fundraising valuation as a reliable estimate of what their options are worth. That can be misleading. A funding valuation results from a particular investment transaction, often involving preferred shares with rights different from employee-held common shares.
The distinction matters because investors may receive liquidation preferences that affect how acquisition proceeds are distributed. A company can sell for a substantial amount without every shareholder receiving a proportional share of the headline price.
As explained in BDC’s explanation of startup employee stock options, employees typically receive rights to purchase shares at a specified exercise price. Vesting, exercise costs and eventual liquidity determine whether those rights produce a financial benefit.
Consider a hypothetical employee initially holding options representing 0.5% of a company. If subsequent financing increases the fully diluted share count while the employee’s option quantity remains unchanged, that percentage decreases. Future option grants or other adjustments could change the result again.
That is why candidates need the number of options, the fully diluted share count, the option pool, the strike price and the relevant share rights. A percentage alone does not establish economic value.
Exit mechanics also matter. Unvested options generally remain subject to the applicable plan and agreement. An acquisition may involve cancellation, replacement, acceleration or other treatment depending on the documents. Employees leaving before an exit may also face a deadline to exercise vested options.
In 2025, the Canadian Venture Capital and Private Equity Association recorded 29 venture-backed exits and no venture-backed IPOs. These industry figures describe a constrained exit environment, not the probability that any particular employee will profit.
The most useful test is simple: would you still accept the position if the equity eventually became worth zero? If the answer is no, the cash compensation and career benefits may not support the decision.
Equity can reward genuine business success, but it should not be entered into your personal budget as a dependable replacement for salary.
How to Evaluate a Canadian Startup Offer in 30 Minutes Using 7 Red Flags and 7 Green Flags?
A Canadian startup offer can receive a useful preliminary assessment in 30 minutes by checking seven warning signs, seven positive indicators and the company’s basic financial disclosures. The objective is not to predict success. It is to identify unacceptable contractual uncertainty, financial fragility and workplace conditions before investing time in deeper negotiations.
Start with the documents, not the founder’s enthusiasm. A compelling mission does not compensate for missing information about what you are being offered.
The following checklist separates problems that require immediate clarification from evidence that makes an offer more credible.
| Area | Red flag | Green flag |
|---|---|---|
| Equity documentation | Only verbal equity promises | Written grant terms or documented grant-approval process |
| Ownership information | Strike price or capitalization details withheld | Clear option count, exercise price and fully diluted ownership information |
| Vesting | Missing terms or an unexplained, unusually long cliff | Understandable vesting schedule, often four years with a one-year cliff |
| Financial runway | Unexplained layoffs or leadership departures alongside funding uncertainty | Management can explain runway and financing history |
| Business traction | No credible revenue, customer or financing path | Verifiable customer demand and progress toward business milestones |
| Job expectations | Unlimited responsibilities disguised as flexibility | Defined priorities, decision rights and realistic workload expectations |
| Recruitment process | Pressure to sign before reviewing documents | Reasonable review time and direct answers to difficult questions |
A four-year vesting schedule with a one-year cliff is a familiar arrangement, not a legal requirement or proof of fairness. Under the example described by BDC, 25% vests after the first year, with the remainder vesting monthly over the following 36 months. Its effect depends on what happens if employment ends or ownership changes.
Use the first 10 minutes to inspect the offer and equity documentation. Spend the next 10 checking public information through relevant federal or provincial corporate registries, available securities filings and the company’s employment history. Federal incorporation records can confirm certain corporate details, but private startup financial statements and capitalization tables are not necessarily public. SEDAR+ is relevant when a company has applicable public securities filings, not as a universal private-startup disclosure database.
Use the final 10 minutes to review employee histories on LinkedIn and prepare targeted questions for management or current and former staff. Ask about departures among engineers and managers, decision-making, cash runway and how priorities have changed over the past year. Public profiles are incomplete, and employee opinions should be treated as individual perspectives.
Your five-step startup offer due-diligence checklist
- Request the equity documentation. Deliverable: a saved offer or grant summary identifying the award type, option count and applicable conditions.
- Establish the exercise economics. Deliverable: a written note showing the strike price, potential exercise cost and disclosed ownership basis.
- Confirm vesting and departure rules. Deliverable: a schedule showing when awards vest and what happens when employment ends.
- Assess business sustainability. Deliverable: a short summary of management’s stated runway, revenue progress and next financing milestone.
- Validate the working environment. Deliverable: written answers about responsibilities, expected hours, reporting relationships and office attendance.
Undocumented equity, an undisclosed strike price and missing vesting terms are reasons not to sign until the gaps are resolved. Layoffs, a modest funding round or a demanding role require investigation rather than automatic rejection.
A short review cannot guarantee a good decision, but it can prevent avoidable surprises before a candidate makes a financially consequential commitment.
Which Is the Better Move in Canada: A Startup Role or a Government Job for Long-Term Stability?
For long-term stability, a Canadian government position with a suitable pension, predictable compensation and strong employment protections may be preferable to a startup role. A startup may instead provide faster skill development, broader responsibility and potential equity gains. The better choice depends on the specific positions, household finances, pension eligibility and personal tolerance for uncertainty.
Compare actual compensation rather than salaries in isolation. A public-sector offer may include a defined-benefit pension, employer-paid benefits and structured progression. A startup package may contain higher potential upside but less predictable benefits and employment continuity.
The federal public service pension is a defined-benefit arrangement under which retirement benefits depend on pensionable service and average salary, as explained in the Government of Canada‘s explanation of the federal public service pension plan.
This federal arrangement should not be assumed to apply to every provincial, municipal or public-sector employer. Pension membership, contributions, benefit formulas and eligibility can differ.
To quantify the financial comparison, separate current spendable income from future retirement benefits. Obtain the actual pension plan’s contribution rates and an individualized pension estimate, then consider your expected years of service and portability if you leave. Do not simply add the employer’s pension contribution to your annual salary and call it guaranteed cash compensation.
Now assess your household’s exposure. A professional with substantial emergency savings, few fixed obligations and easily transferable skills may tolerate a risky pre-seed position. Someone carrying a mortgage or supporting dependents may place a greater premium on predictable earnings.
Company maturity complicates the comparison. A pre-seed startup facing an imminent financing requirement is not equivalent to a later-stage business with established revenue. Neither startup funding nor government employment provides an unconditional guarantee of job security.
Career mobility provides a middle path. Startup employees can later pursue public-sector or larger-company positions, while public employees can move toward private-sector opportunities. However, these transitions may require different technical, management or procurement experience.
The five-year career question is especially useful: which position will produce stronger demonstrated skills, professional relationships and future employment options? A startup might accelerate responsibility while exposing employees to irregular working hours. A public-sector role might offer clearer progression and, where applicable, collective agreement protections.
A government role may be the stronger financial foundation, while a startup can be the stronger learning opportunity. The decision becomes clearer when future mobility and actual employment conditions receive as much weight as compensation.
The Equity Paperwork Mistake That Can Surprise Canadian Startup Employees at Tax Time
The costly paperwork mistake is exercising startup stock options without first confirming when the taxable employment benefit arises. Canadian tax treatment depends partly on whether the employer is a qualifying Canadian-controlled private corporation. Some exercises can create taxable benefits before shares become liquid, potentially leaving employees with a tax obligation but no proceeds from a share sale.
Employee options are not taxed identically under every arrangement. The legal classification of the employer, option terms and relevant statutory conditions determine the treatment.
Under CRA guidance on employee stock-option taxation, a qualifying Canadian-controlled private corporation arrangement generally results in recognition of the employment benefit when shares are disposed of. For non-CCPC arrangements, the benefit is generally recognized when shares are acquired through exercise.
That distinction is essential. It would be incorrect to assume every Canadian startup employee owes tax immediately when exercising options. It would be equally risky to assume an exercise never creates a current-year tax issue.
Consider a hypothetical grant of 2,000 options with a $5 CAD exercise price. Exercising every option requires $10,000 CAD to acquire the shares, excluding other costs. Whether an additional taxable benefit arises at exercise, and how it is calculated, depends on the applicable tax rules and the relevant share value.
The cash-flow risk becomes more serious when a private company’s shares cannot readily be sold. A taxable benefit recognized before liquidity may require payment from savings or other available funds. Selling shares to cover the liability may be impossible or commercially unattractive.
Cross-border employment adds another layer. A Canadian employee working temporarily outside Canada, receiving options from a US-linked entity or holding shares under a multinational structure may encounter additional tax or reporting questions. Residency, where services were performed and the legal issuing entity can matter. These situations require individual professional review rather than assumptions based solely on the employer’s headquarters.
Before accepting or exercising options, obtain the grant agreement, vesting schedule, exercise price, expiry and departure provisions, and the company’s explanation of the plan’s Canadian tax treatment.
Ask the finance team which legal entity grants the options, whether it is treated as a CCPC for the relevant purposes, what share valuation is used, when an employment benefit may be reported and whether withholding or payroll reporting is expected.
Confirm those answers with a qualified Canadian tax professional, particularly for significant option exercises or cross-border situations. A tax preparer may need time to review the documents before an exercise deadline.
The important deadline is not necessarily tax-filing season. It is the point before exercise when you can still assess the financial and tax consequences of the transaction.
When Is the Best Time to Join a Canadian Startup: Pre-Seed, Series A, or Later?
The best time to join a Canadian startup depends on your ability to absorb risk and the kind of work you want. Pre-seed roles may offer greater ownership potential and creative freedom but substantial uncertainty. Series A can provide more organizational structure, while later-stage companies may offer clearer responsibilities and stronger cash compensation. None of these funding stages guarantees success.
Funding stages are useful indicators of business development, but they are not substitutes for financial due diligence. A company labelled pre-seed may already have meaningful revenue, while a Series A company can still face difficult product, sales or fundraising challenges.
The following comparison describes common tendencies rather than rules that apply to every employer.
| Decision factor | Pre-seed | Series A | Later stage |
|---|---|---|---|
| Equity opportunity | Potentially larger ownership percentage | Often smaller percentage as ownership broadens | May be smaller with a higher exercise price |
| Cash compensation | Often constrained | May become more competitive | Potentially closer to established-market compensation |
| Role clarity | Frequently evolving | Growing specialization | Usually more defined |
| Business uncertainty | High uncertainty around commercial viability | Continuing execution and scaling risk | Potentially greater maturity, with remaining financial risk |
| Personal influence | Broad opportunity to shape operations | Meaningful influence within a growing organization | More specialized influence |
Early employees may receive options at relatively low strike prices, but an early grant is not automatically valuable. Future dilution, business performance and share rights determine its eventual economic outcome.
Later-stage candidates face a different problem. A grant priced near a high valuation could become underwater after a down round, meaning the current share value falls below the exercise price. A more mature company can still offer unattractive equity economics.
When interviewing, ask how many months of cash runway remain, what operating milestones the current financing must support, whether previous rounds diluted employee ownership and what evidence demonstrates customer demand.
Canadian funding conditions add an important qualification. The CVCA’s 2025 market overview recorded $8.0 billion CAD of venture investment across 571 deals. Series A through Series D investment declined relative to 2024, while growth-stage investment increased. These aggregate patterns do not establish the financing prospects of any individual startup.
Waiting for a later funding stage can reduce certain uncertainties but does not eliminate exposure to downturns or layoffs. Likewise, joining early may be worthwhile for a candidate motivated by broad responsibilities even if the equity never pays out.
The strongest entry point is the one where the actual business risks, compensation and responsibilities fit your circumstances—not necessarily the earliest or most heavily funded company.
Why Do Jobs Cluster in the Toronto–Waterloo Corridor Instead of Spreading Across Ontario?
Startup jobs cluster in the Toronto–Waterloo corridor because concentrated talent, investors, universities and experienced company operators make it easier for businesses to recruit, exchange knowledge and raise capital. As more companies operate nearby, workers gain alternative employment opportunities and founders gain access to specialized experience. The resulting network can reinforce its own geographic concentration.
The corridor’s advantage is not simply the distance between Toronto and Waterloo. It is the practical ability to access people with relevant technical, commercial and operational experience.
A founder recruiting an engineering leader may benefit from nearby professionals who have scaled comparable businesses. Employees, in turn, may benefit from having several potential employers within a workable geographic area.
This creates a significant consideration for anyone accepting a 15% salary reduction. If the startup closes or restructures, access to alternative roles can reduce the professional disruption of losing that position.
However, geographic proximity does not guarantee a quick replacement job, and employment networks cannot eliminate the financial effects of a period without income.
The Canadian market provides some supporting regional context. CVCA reported that Ontario received just over half of Canadian venture capital dollars invested during 2025. That figure covers the whole province, not specifically Toronto–Waterloo, and investment concentration does not directly measure employment concentration.
There are meaningful alternatives outside the corridor. Ottawa, Montreal, Vancouver and Calgary offer their own technology and startup opportunities, while remote employment can widen the pool available to candidates unwilling to relocate.
Remote policies should nevertheless be verified at the team level. A job posting may advertise flexibility without establishing whether leadership opportunities, promotions and collaboration operate equally for employees outside a particular office.
For a candidate based in Montreal or Vancouver, the relevant question is not whether Toronto–Waterloo is objectively superior. It is whether the startup’s location creates career advantages sufficient to justify relocation, travel or a narrower local employment network.
The same applies to professionals living outside major urban centres. When accessible alternatives are limited, the quality of a single offer becomes more important because switching employers may be harder.
Geography is a form of career risk management, but any benefit from proximity must be weighed against housing, commuting and the working arrangements the employer will actually support.
Why Do Canadian Startups Raise Smaller Rounds Even With Strong Traction?
A Canadian startup may raise a smaller financing round despite strong customer traction because funding size reflects investor availability, financing strategy, geography and capital requirements—not just product quality. Canada’s venture funding environment differs from that of the United States, and companies may pursue capital-efficient growth. For employees, the relevant measures are cash runway and future funding needs.
Canada’s domestic venture capital market has a different scale and investor composition from the US market. Access to large investment funds, international investor relationships and competition for specific deals can influence how much capital a company raises.
A modest round is therefore not automatically evidence of weak demand. A company generating revenue while controlling operating expenses may require less external financing than a business investing aggressively in expansion.
Equally, a large round does not prove sustainability. High spending can consume substantial financing while leaving the business dependent on another raise.
$8.0 billion CAD
Venture capital invested across 571 Canadian deals in 2025, according to CVCA. The reported full-year average deal size was $14.07 million CAD. These figures are national market observations, not a benchmark for an individual startup’s financial health.
Canadian Venture Capital and Private Equity Association, 2025 year-end market report.
For an employee, round size becomes useful only after connecting it to the company’s spending and cash position.
Consider this explicitly hypothetical scenario: a startup has $3 million CAD available and spends a net $250,000 CAD per month. Dividing available cash by monthly net burn gives approximately 12 months of runway, assuming spending and cash inflows remain unchanged.
The example is not a forecast. It illustrates why knowing that a company raised $3 million is insufficient. Some of the funding may already have been spent, revenue may change and management may adjust hiring or operating costs.
Ask management for current available cash, net monthly burn, approximate runway and the milestones required before the next financing decision. Team size helps interpret spending, but it cannot independently establish runway because compensation, infrastructure and other expenses vary.
Frequent capital raises may also affect employee ownership through dilution. The extent depends on the financing structure, share issuances and any adjustments to existing option grants.
In a market where employees cannot count on a rapid exit, accepting significantly lower cash compensation deserves particular scrutiny. Negotiating a stronger base salary, a review date or clearer option terms can reduce dependence on hypothetical future proceeds.
Financial transparency matters more than a headline fundraising number. A smaller, sustainable company may be more suitable than a larger-funded business whose next financing milestone is uncertain.
Key takeaways before comparing offers
- A 15% salary reduction is a measurable financial sacrifice; startup equity remains an uncertain future outcome.
- Company runway and employment alternatives influence the consequences of a failed startup, but neither removes personal financial exposure.
- Location and commuting requirements can change the effective value of an offer even when the published salaries remain identical.
Is the Toronto–Waterloo Corridor Worth the Commute if It Adds 8 Hours a Week?
An additional eight hours of commuting per week can materially reduce the attractiveness of a Toronto–Waterloo startup offer, especially when the position already pays 15% less. The commute may still be worthwhile for significant career development or valuable in-person collaboration. Its real cost depends on travel frequency, transport expenses, flexibility and the employee’s available personal time.
Eight extra weekly hours should be treated as an individual scenario, not a typical commuting time for workers in the corridor. Actual journeys differ considerably according to home location, workplace, office days and transportation choices.
Using a hypothetical schedule of 48 working weeks annually, eight additional commuting hours per week equals 384 hours a year. That is time unavailable for personal activities, family responsibilities or rest.
Compare that commitment against the salary reduction using a consistent annual framework.
| Factor | Current position | Startup offer |
|---|---|---|
| Annual base salary | $120,000 CAD | $102,000 CAD |
| Gross salary difference | Baseline | -$18,000 CAD annually |
| Equity | None assumed | Uncertain value; terms require review |
| Additional commute | Baseline | 8 hours weekly, as assumed |
| Additional annual travel time | Baseline | 384 hours, assuming 48 working weeks |
| Travel expenses | Existing costs | Calculate incremental fares, fuel, parking and other costs |
| Benefits and flexibility | Verify existing package | Confirm proposed arrangements in writing |
These figures are illustrative, not representative market salaries or universal commuting estimates. The $18,000 salary difference is before tax, while the actual change in take-home pay depends on the employee’s tax circumstances.
The commute also changes the amount of time effectively committed to employment. A role requiring long office hours plus substantial travel may provide less personal flexibility than a similar job located nearby.
Hybrid arrangements can alter the calculation significantly. Two or three office days per week may be workable for someone who would reject five days of lengthy travel. The relevant question is whether that schedule is an enforceable or dependable working expectation rather than an informal recruitment promise.
Ask the hiring manager which days require attendance, whether senior employees follow the same policy, how often unexpected office visits occur and whether the arrangement may change.
Employees should also examine second-order costs. Long journeys can affect sleep, childcare logistics, energy and willingness to participate in the additional work sometimes expected at growing startups.
Possible alternatives include negotiating a higher salary, fewer office days, different working hours or assistance with relocation. None is guaranteed, but each is a legitimate component of the overall employment discussion.
The decision should ultimately account for realistic fallback opportunities. A corridor location may improve access to future employers while still imposing substantial recurring costs in the current role.
Before accepting, create a personal comparison using both written offers, realistic weekly hours and actual travel expenses. If the startup remains attractive when equity is valued at zero, the career opportunity may justify a closer look. If it only works financially under a successful exit, negotiate the cash package or reconsider the offer.
How much additional startup equity compensates for a 15% salary cut?
There is no universally reliable equity percentage that compensates for a 15% salary reduction. A fair comparison requires the option count, exercise price, fully diluted capitalization, share rights, vesting conditions and realistic liquidity scenarios. Because a private company’s equity can become worthless, it should not be valued as guaranteed salary.
Can you negotiate both salary and equity at a Canadian startup?
Yes. Candidates can request adjustments to base salary, equity quantity, grant terms or compensation review timing. Whether the employer can agree depends on its compensation policies, financing position and required approvals. Obtain any agreed changes in written documentation rather than relying on verbal assurances.
What happens to stock options if you leave a Canadian startup?
The outcome depends on the equity plan and grant agreement. Unvested options may be forfeited, while vested options can be subject to a post-termination exercise deadline. Employees should confirm applicable deadlines, exercise costs and restrictions on selling the resulting shares before leaving.
Is startup equity taxed differently in Quebec and Ontario?
Federal employee stock-option rules apply across Canada, but provincial income-tax treatment and reporting can affect the final outcome. Quebec employees may face different provincial considerations from Ontario employees. The employer’s classification, award structure and personal circumstances also matter. A qualified tax professional should review the specific arrangement before exercise.
Should you accept startup equity if you plan to leave Canada?
International mobility makes the decision more complex. Future residence, work location, the issuing company and the timing of vesting or exercise may affect tax treatment and reporting. Before moving or exercising options, obtain the plan documents and consult a professional familiar with the relevant countries. Do not assume that an option grant retains the same after-tax value after relocation.