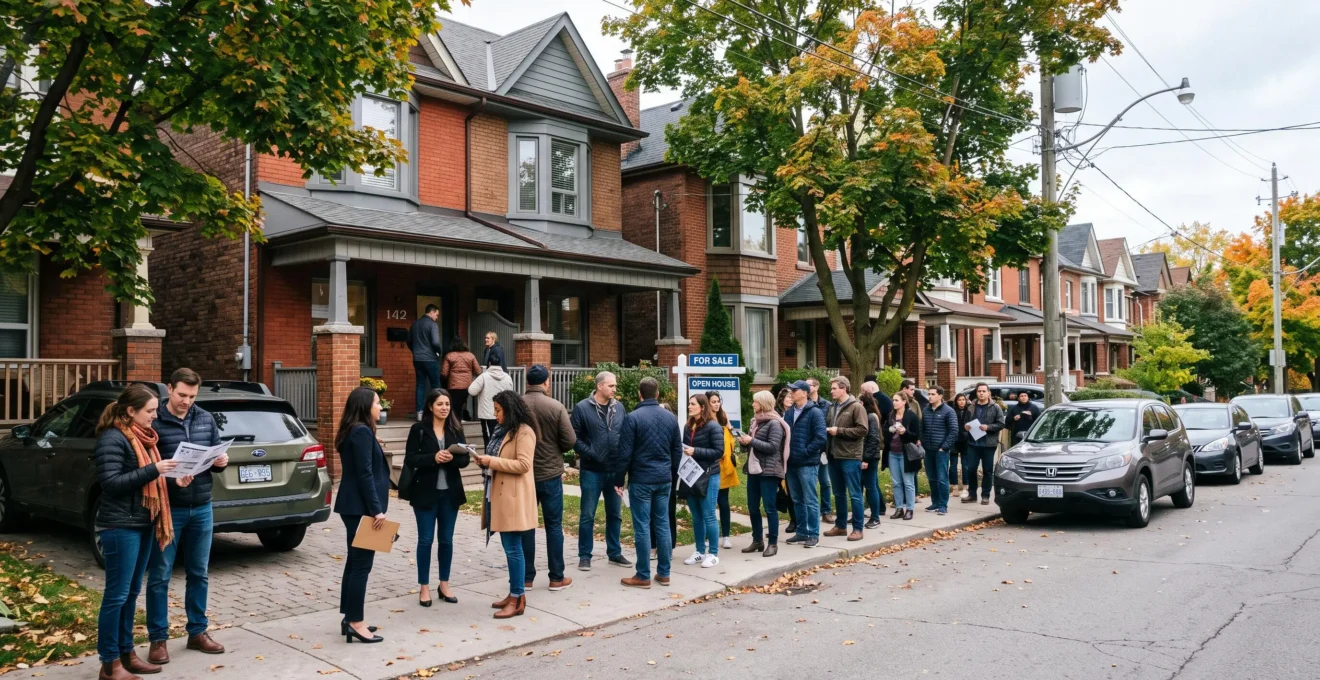
A two-percentage-point increase in mortgage rates can substantially reduce how much a Canadian household can borrow. Yet it does not automatically eliminate the need for housing, create more available homes, or remove competition for desirable properties.
Housing demand can remain structurally strong even when purchasing activity slows. People still need somewhere to live, households continue to form, and buyers with substantial equity or cash are less exposed to mortgage-rate changes. When suitable listings remain scarce, competition can persist despite weaker affordability.
That does not mean Canadian home prices always rise or bidding wars continue everywhere. In September 2026, the Canadian Real Estate Association reported relatively balanced national inventory alongside declining home price indicators. Local conditions can be considerably different.
For renters, first-time buyers and people considering a move, the useful question is not simply whether housing demand is high. It is whether demand for the specific type of home, neighbourhood and price range they need exceeds available supply—and whether buying remains financially sensible.
Canadian housing demand: what matters most
- Higher interest rates reduce borrowing power, but housing needs, accumulated homeowner equity and limited supply can sustain competition.
- National headlines cannot establish local conditions. Compare inventory, days on market and selling prices across neighbourhoods before deciding.
- Renting, buying a starter home or choosing a condo should depend on total costs, financial flexibility and expected time in the property—not predictions about mortgage rates alone.
- Why Do Canadian Cities Still Have Bidding Wars Even After Rate Hikes?
- How to Measure Housing Demand in Your Canadian Neighbourhood Without Being a Real Estate Insider?
- Which Is Smarter in Canada Right Now: Renting for 3 Years or Buying a Starter Home?
- The Housing Demand Mistake That Makes Canadians Overpay in the Wrong Neighbourhood
- When Should You Start House Hunting in Canada to Face Fewer Competing Offers?
- Why Are Condos Everywhere in Canadian Cities Even When People Want Houses?
- Why Did Rent in Your Canadian City Jump 10% Even if Your Building Didn’t Improve?
- Is a Condo in Canada Still a Good Idea When Fees Add $600 CAD a Month?
Why Do Canadian Cities Still Have Bidding Wars Even After Rate Hikes?
Canadian cities can experience bidding wars after interest-rate increases because higher borrowing costs reduce purchasing power without necessarily increasing the supply of desirable homes. Buyers with cash, substantial equity or strong incomes may remain active while mortgage-dependent buyers withdraw. Competition can therefore persist for scarce starter homes or well-located properties, even when the broader market slows.
Consider a hypothetical market with fewer active buyers than a year earlier but an equally limited selection of family-sized homes near transit and schools. Although total demand has weakened, several qualified households may still pursue the same listing. The competition reflects scarcity within that segment, not necessarily a booming citywide housing market.
A two-percentage-point mortgage-rate increase can have a particularly strong effect on first-time buyers. Higher financing costs reduce affordability and may prevent households from qualifying for their preferred purchase price. Existing homeowners moving to smaller properties, however, may have equity from a previous sale. Cash purchasers are even less directly exposed to borrowing costs.
Rate increases change who can compete as well as how much buyers can offer. They do not remove demand from people who still need a home but can no longer qualify for a mortgage. Some remain renters, extending demand pressure into another part of the housing market.
Canada’s longer-term supply challenge adds another dimension. CMHC’s Fall 2026 Housing Supply Report estimates that approximately 417,000 to 469,000 new homes would be needed annually to restore pre-pandemic affordability by 2036. This is a projected construction requirement, not a count of homes currently missing from listings.
417,000–469,000 homes annually
CMHC’s estimated annual new-home requirement to restore pre-pandemic affordability by 2036. The estimate concerns long-term national supply needs, not current bidding-war frequency.
Canada Mortgage and Housing Corporation, Fall 2026 Housing Supply Report.
Population growth, immigration and movement between provinces can also affect where households seek accommodation. These forces can support underlying housing needs, but their local impact depends on actual population changes, incomes, housing completions and the types of dwellings available. National immigration targets should not be treated as a fixed forecast of neighbourhood-level demand.
Recent resale data provide an important counterweight to claims of uniformly intense competition. CREA reported months of inventory nationally 4.9 months of inventory September 2026, broadly consistent with its historical average. The National Composite MLS Home Price Index declined 0.4% from August and was 3.4% below September 2025 on an unadjusted annual comparison.
Those figures are inconsistent with treating Canada as a single market experiencing uninterrupted price growth. Toronto, Vancouver, Calgary and smaller municipalities can differ in available inventory, property mix and buyer competition. Even within one city, an entry-level house and an expensive condo may behave differently.
The practical lesson is to distinguish the lasting need for housing from actual purchasing activity. A constrained supply of homes can support competition, but local transaction data are necessary before deciding that any particular property deserves an aggressive offer.
How to Measure Housing Demand in Your Canadian Neighbourhood Without Being a Real Estate Insider?
You can estimate neighbourhood housing demand by tracking four indicators: days on market, sale-to-list price ratios, active listings relative to sales, and evidence of competing offers. Compare similar property types over three to six months instead of relying on one listing or a national headline. This reveals whether competition is strengthening, weakening or remaining relatively stable.
Start with CREA’s September 2026 housing market statistics and local real estate board publications to establish the broader context. CMHC reports offer additional information about construction, rental conditions and supply trends. REALTOR.ca provides current listings and some property history, although detailed sold-price information and listing histories are not consistently available in every market.
Four indicators are especially useful when they are measured consistently for comparable homes.
| Indicator | What to look for | How to interpret it |
|---|---|---|
| Days on market | Whether comparable homes are selling more quickly or slowly | Shortening marketing periods may indicate stronger competition, especially when inventory is also falling. |
| Sale-to-list price ratio | Actual sale price divided by the final asking price | A ratio above 100% shows sales above asking, but strategic underpricing can distort the signal. |
| Months of inventory | Active listings relative to the recent monthly sales pace | Lower inventory generally means fewer available choices per active buyer. |
| Multiple-offer activity | Whether comparable listings regularly attract competing offers | Repeated competition on similar properties is more informative than one crowded open house. |
CREA’s national methodology identifies inventory below 3.6 months as consistent with seller-market conditions and above 6.4 months with buyer-market conditions, based on historical statistical relationships. These are national reference points, not universally applicable thresholds for individual streets.
Be careful with sale-to-list ratios. A home deliberately advertised below its expected market value may attract offers above asking without selling above what comparable properties are worth. A ratio above 100% is a clue about marketing and competition, not proof of overvaluation or a housing shortage.
Similarly, a busy open house may reflect curiosity rather than qualified purchasing demand. Ask a local agent about actual competing offers on recent comparable sales, and check whether properties are being relisted or having prices reduced. Treat undocumented offer-count claims as anecdotal.
National media coverage describes aggregated activity. Your decision requires a smaller geographic and financial comparison, ideally using the same home type, similar condition and comparable budget across two or three neighbourhoods.
Build a neighbourhood demand comparison in five steps
- Select three candidate neighbourhoods and one comparable housing type. Deliverable: a shortlist containing location, property type and maximum budget.
- Record available active listing counts and recent sales for each area. Deliverable: a dated inventory comparison with data sources identified.
- Collect recent days-on-market and sale-to-list figures where reliable local records are available. Deliverable: a three-to-six-month trend table, with missing observations clearly marked.
- Review recent comparable listings for price reductions, relistings and confirmed competing offers. Deliverable: a brief evidence log distinguishing verified sales from anecdotal reports.
- Compare the three neighbourhoods against your budget and requirements. Deliverable: a ranked shortlist explaining which locations offer the strongest balance of affordability, selection and competition.
The most useful result is not a claim that one neighbourhood is universally better. It is a documented explanation of where your preferred home type is more readily available—and where competition may justify a more cautious offer strategy.
Which Is Smarter in Canada Right Now: Renting for 3 Years or Buying a Starter Home?
Renting for three years may be financially smarter when a move is likely, ownership costs substantially exceed rent, or purchasing would exhaust emergency savings. Buying becomes more compelling when income is stable, the home meets longer-term needs and the expected financial benefits outweigh closing, financing, maintenance and eventual resale costs. Neither choice is automatically superior in Canada.
The mistake is comparing rent only with a mortgage payment. Ownership involves property taxes, home insurance, utilities, maintenance and, for a condo, monthly fees. Mortgage payments also contain both interest and principal. Principal repayment generally builds equity, while interest is a financing expense.
During the earlier years of a conventional amortizing mortgage, the interest component may be substantial, depending on the mortgage rate and amortization schedule. Therefore, a mortgage payment is neither entirely an expense nor entirely a form of saving.
The Financial Consumer Agency of Canada provides official guidance on the full costs of buying a home. It recommends allowing approximately 1.5% to 4% of the purchase price for upfront closing costs, which can include legal expenses, inspections and other transaction charges.
Canadian buyers must also account for jurisdiction-specific costs. Land transfer taxes can be significant in Ontario and British Columbia, and Toronto has an additional municipal land transfer tax. Applicable exemptions or rebates depend on eligibility and location. If the buyer sells after a short ownership period, selling expenses—including negotiated real estate commissions and legal costs—may further reduce the financial return.
Consider this explicitly hypothetical comparison, which illustrates cash flow rather than forecasting real market prices.
Hypothetical three-year housing comparison
A renter pays CAD 2,300 per month, while a comparable home has a CAD 2,700 monthly mortgage payment plus CAD 700 in taxes, insurance, maintenance and other ownership costs. The renter’s illustrative housing cash outflow is CAD 82,800 over 36 months, compared with CAD 122,400 for the owner before initial purchase and eventual selling costs.
The CAD 39,600 difference in cash outflow is not a net wealth comparison. The owner repays some mortgage principal and may experience property appreciation or depreciation; the renter may earn returns on funds not committed to a down payment. A complete decision requires an amortization schedule, transaction-cost estimates and assumptions about future property value and savings returns.
Renting preserves flexibility if employment, family circumstances or preferred location changes. It also avoids direct exposure to a decline in the property’s sale price. However, renters can face market rent increases when moving, subject to applicable provincial laws and tenancy protections.
Three questions help determine the better option: Is a move within three years realistic? Would the purchase leave enough savings for unexpected costs? And does the local purchase price make sense relative to the rent for a genuinely comparable home?
Financial security matters more than winning an argument about whether Canadian property values will rise. A home that fits a household’s budget and likely holding period may be appropriate even without a rapid increase in value.
When the expected stay is short, transaction costs and mobility deserve substantial weight. When the expected stay is longer, affordability is secure and the property meets future needs, ownership may provide benefits that a simple monthly cost comparison cannot capture.
The Housing Demand Mistake That Makes Canadians Overpay in the Wrong Neighbourhood
One costly housing-demand mistake is confusing a neighbourhood’s popularity with its suitability. Buyers may compete for highly regarded districts because of their reputation, school rankings or previous price growth, even when they do not need the features driving the premium. This concentrates competition and can produce unnecessarily expensive purchases without improving daily life.
Demand is meaningful only in relation to what a household needs. A buyer who works remotely may gain little from paying extra to live beside a major commuter station. Another household may value access to that station more than additional square footage.
The same principle applies to school catchments, nightlife, parks and prestigious addresses. A feature that supports resale demand does not necessarily justify its full price premium for every buyer.
Begin by separating functional requirements from preferences that mainly reflect reputation.
| Decision factor | Practical requirement | Potentially unnecessary premium |
|---|---|---|
| Commute | A reliable journey that fits the household’s work schedule | Paying for central access that is rarely used |
| Space | Bedrooms, storage and flexibility for foreseeable needs | Buying extra space solely to match expectations |
| Services | Accessible groceries, healthcare, childcare or other essentials | Choosing a prestigious retail district over ordinary convenience |
| Schools | Suitable educational access where relevant | Paying a school-catchment premium without needing that access |
| Neighbourhood reputation | Safety, practicality and a suitable living environment | Assuming a famous address necessarily offers better value |
Test the real commute during the hours you would normally travel. Consider space requirements over approximately five years rather than focusing exclusively on the immediate move. Compare access to essential services in adjacent neighbourhoods, including the time required to reach them.
Price per square foot is useful only after adjusting for what you are comparing. Building condition, property type, usable space, transit access, maintenance exposure and local amenities can make a cheaper home less attractive or a more expensive one better suited to your needs.
The pressure to win a popular property introduces another risk. Buyers who become attached to one neighbourhood may exceed their budget or waive financing and inspection conditions to compete. That can expose them to mortgage-approval problems or unexpected repairs.
Research future changes as well as current reputation. Planned transit improvements, permitted development, infrastructure investment and school capacity may influence a neighbourhood’s future appeal. These should be checked against official municipal planning information, since a proposed improvement is not a guaranteed completed project or price increase.
Rather than predicting which neighbourhood will become fashionable, consider whether an alternative area can meet your needs at a more sustainable total cost.
Buyers who define value around their own circumstances can widen their search without abandoning important requirements. This also gives them a clearer reason to walk away when a property’s asking price or competition becomes difficult to justify.
When Should You Start House Hunting in Canada to Face Fewer Competing Offers?
Winter can offer fewer competing buyers in some Canadian markets, while spring and early fall often bring more listings and more active purchasers. However, quieter periods also provide less choice, so lower competition is not guaranteed. The strongest strategy is to prepare financing and neighbourhood research before the busy season, then search when suitable properties and personal readiness align.
Seasonality affects both sides of the housing market. As more homeowners list properties in spring, buyers may have a wider selection. Yet the number of active shoppers can also increase, particularly for well-priced homes in desirable locations.
Winter may reduce competition from households that prefer not to move during cold weather or the school year. In exchange, fewer owners may list their homes. This can be especially important if the buyer needs a particular number of bedrooms, accessible layout or limited geographic area.
There is no universal best month for purchasing a home in Canada. Weather, school calendars, local employment patterns and regional market conditions can change the relationship between listings and competing buyers.
A more dependable approach is to prepare before searching intensively:
- Review income, debts, savings and the maximum affordable monthly housing cost.
- Obtain a mortgage pre-approval where appropriate, understanding that final approval depends on the property and lender requirements.
- Confirm the available down payment and reserve enough funds for closing and emergencies.
- Identify acceptable neighbourhoods and verify recent comparable sale prices.
- Set a firm maximum offer and decide which contractual conditions are necessary before viewing a competitive property.
Waiting for lower mortgage rates can appear attractive because a lower rate may improve borrowing capacity. However, falling rates can also encourage buyers who previously postponed their searches to return. If listings do not increase correspondingly, competition can intensify.
This does not mean lower rates inevitably cause bidding wars. Income trends, consumer confidence, supply and local employment also influence buyer behaviour. The important point is that future financing conditions cannot be evaluated independently of future property prices and competition.
Listing freshness matters, too. In active neighbourhoods, some sellers establish offer-review dates to concentrate interest shortly after a listing appears. Others accept offers as they arrive. Buyers should understand the specific process instead of assuming that every property requires an immediate unconditional bid.
Allow enough time to examine comparable sales and inspection options. Missing a property is generally preferable to accepting a financial commitment that exceeds a carefully established budget.
Preparation does not guarantee fewer competing offers, but it makes competition easier to evaluate. A buyer who knows their budget, alternatives and limits can respond to a suitable listing without treating every opportunity as their last.
Why Are Condos Everywhere in Canadian Cities Even When People Want Houses?
Condominiums are widespread in major Canadian cities partly because expensive urban land, planning rules and demand for centrally located housing make higher-density development more practical than building detached houses. Condo supply reflects the interaction between construction economics, municipal permissions and market demand—not necessarily the ideal housing preferences of every household.
Where developable land is scarce and ground-oriented housing is expensive, building multiple units on one parcel allows developers to distribute land costs across more homes. Municipal densification policies can support this form of development, although zoning, infrastructure requirements and project economics differ by location.
Developers also respond to what buyers can finance. A smaller apartment may fall within the purchasing budget of households that cannot afford a detached home in the same area. The result can be an ownership market dominated by condos even when many residents would prefer a house with private outdoor space.
Condo construction can help accommodate population growth and provide alternatives to low-density housing. But one newly built condo does not necessarily substitute for one family-sized house. Unit size, layout, accessibility and location determine which households can realistically use the new supply.
Condos also create a different ownership arrangement. Buyers usually own their unit while sharing responsibility for common property through a condominium or strata corporation. Recurring fees help maintain shared assets, and additional assessments may be required when available funds are insufficient for major expenses.
Before purchasing, request the relevant condominium disclosure and financial documents. In Ontario, these commonly include a status certificate. Other provinces have different document names and requirements, including strata documentation in British Columbia.
Review the reserve fund, financial statements, insurance arrangements, planned repairs, current or proposed special assessments and applicable rules. Depending on the jurisdiction and building, restrictions may affect pets, alterations and rentals. Buyers should verify the actual governing documents rather than assuming that all Canadian condos operate alike.
Investor demand adds another dimension. Some individual investors purchase condos as rental properties, making condos part of both the ownership and rental housing markets. Their activity can affect sales and rental supply, but it should not be assumed to determine every building’s price trend.
CMHC’s Fall 2026 supply research identifies weaker condominium and ground-oriented construction in several major metropolitan markets. It also warns that reduced construction during softer market conditions can create longer-term ownership supply challenges when demand recovers.
At the same time, condo resale prices can soften in a market where available units exceed active buyer interest, even while detached homes elsewhere remain relatively scarce. National housing shortages therefore do not guarantee strong appreciation for every condo.
A condo can be a suitable first home, but buyers should evaluate the actual unit, building finances and likely holding period rather than treating higher-density housing as an automatic solution to affordability.
Why Did Rent in Your Canadian City Jump 10% Even if Your Building Didn’t Improve?
A rental price can rise by 10% without any building improvements because landlords generally assess market rents based on demand for comparable available units, not solely on the condition of an individual property. However, a 10% increase is illustrative, not a universal Canadian trend or automatically lawful rent increase. Provincial regulations and tenancy circumstances determine what a landlord may charge.
Housing demand influences rents through several channels. New households require accommodation, while some prospective buyers remain renters when mortgage qualification becomes more difficult. If available rental supply does not keep pace with these needs, competition for vacant units may support higher asking rents.
That does not mean rents necessarily rise during every period of strong population growth. New rental construction, changing migration patterns, affordability limits and local economic conditions can also moderate or reverse increases.
Another important distinction is the difference between market asking rents and increases charged to existing tenants. In provinces with applicable rent controls, a landlord may face restrictions when raising rent during an ongoing tenancy, even while comparable vacant units are advertised at substantially different prices.
Ontario provides a useful example. Its 2026 residential rent increase guideline is 2.1% for most covered tenancies, while the announced 2027 guideline is 1.9%. The rules include important exemptions, including certain units first occupied for residential purposes after November 15, 2018.
Under Ontario’s general framework, eligible rent increases ordinarily require at least 90 days’ written notice, and at least 12 months must usually have passed since the tenancy began or the previous increase. Certain above-guideline increases can be authorized through the applicable process.
Ontario’s official residential rent increase rules explain the guideline, exemptions and notice requirements. Those rules should not be generalized to British Columbia, Alberta, Quebec or other jurisdictions, each of which has its own tenancy framework.
For example, consider two hypothetical otherwise identical apartments in one building. A long-term tenant may pay a lower rent because applicable increases have been restricted over time. A newly available apartment may be advertised at a substantially higher rent based on current market conditions. The difference does not necessarily reflect renovations or better amenities.
Before accepting a proposed increase, identify whether it concerns an existing tenancy or a new rental agreement. Then confirm the province’s rules, the type and age of the unit where relevant, any applicable exemptions, the required notice and whether special authorization is necessary.
Compare similar nearby units using the same number of bedrooms, approximate size, location, condition and included utilities. An advertised price is not proof of the final rent agreed upon, but it can provide useful context when negotiating or evaluating a move.
The central lesson is that a landlord’s perception of market demand does not replace tenancy law. Renters should assess the actual market and their legal position separately, especially before signing an agreement or giving notice to leave.
Key takeaways before choosing a condo
- Compare the full monthly cost of a condo with other realistic housing options, not just its mortgage payment.
- Investigate reserve fund health and potential major repairs; a low advertised fee does not necessarily mean low ownership risk.
- Think about future resale demand and affordability if fees increase, especially when the condo is intended as a starter home.
Is a Condo in Canada Still a Good Idea When Fees Add $600 CAD a Month?
A Canadian condo can still be a sensible purchase with CAD 600 in monthly fees if the total ownership cost is affordable and the building’s finances are sound. Fees often cover expenses that a detached-home owner would pay separately. The decision depends on what the fees include, whether the reserve fund is adequately financed and how future increases could affect affordability.
The CAD 600 figure is an example, not a standard Canadian condo fee. Actual charges vary by unit size, building age, amenities, insurance costs, maintenance requirements and financial decisions made by the condominium corporation.
Fees commonly help pay for shared building insurance, cleaning, utilities for common areas, building management, routine maintenance and contributions to a reserve fund for major repairs. The precise coverage depends on the building.
Some condo fees may include heating, water or other services that would otherwise appear as separate household bills. Others exclude most utilities. Comparing advertised fees without identifying these differences can be misleading.
Consider the following hypothetical monthly comparison. The figures are illustrative and are not presented as current market averages.
| Cost category | Condo | Freehold house |
|---|---|---|
| Mortgage payment | CAD 2,200 | CAD 2,500 |
| Condo fees | CAD 600 | CAD 0 |
| Property taxes | CAD 250 | CAD 350 |
| Unit or home insurance | CAD 50 | CAD 150 |
| Additional maintenance allowance | CAD 75 | CAD 300 |
| Total illustrated monthly outflow | CAD 3,175 | CAD 3,300 |
This simplified scenario excludes separately billed utilities, transaction costs and any expenses already covered by the condo fees. It also assumes no unexpected special assessments or major house repairs. The houses are not assumed to have equivalent market values, so the table illustrates budgeting mechanics rather than proving one property type is financially superior.
For the condo, the most important risk may not be today’s CAD 600 payment. An aging building could face higher maintenance, insurance or energy costs. If the reserve fund is insufficient, owners may need to contribute through higher recurring fees or special assessments.
Unusually low condo fees deserve scrutiny, not automatic praise. They may reflect an efficient building, limited amenities or a smaller maintenance burden, but they can also indicate inadequate financial provisions.
Before purchasing, compare the building’s fee structure with similar nearby properties and review its reserve fund documentation, financial statements, operating budget, insurance information and known future capital projects. Obtain appropriate professional advice when financial or legal documents reveal material concerns.
Fees can also affect resale. Future buyers must assess the same monthly obligations, and lenders may include condo fees in mortgage affordability calculations. Higher charges can narrow the pool of households able or willing to purchase the unit, although the impact depends on the services included and competing property costs.
Condo ownership can remain a practical entry point in cities where detached housing is financially inaccessible. The objective is not to avoid fees altogether, but to understand the services purchased and the potential financial obligations attached to shared ownership.
Before making an offer, prepare a complete housing budget, obtain the building’s financial and legal documents, and test whether your finances could absorb both a fee increase and an unexpected assessment. A condo is a stronger choice when its risks and benefits remain acceptable beyond the first year of ownership.
Does a two-percentage-point mortgage rate increase mean Canadian house prices must fall?
No. Higher rates generally reduce mortgage affordability and can weaken purchasing demand, but prices also depend on available listings, income, employment and the property types buyers want. Some markets can experience price declines while individual neighbourhoods or housing segments remain competitive. A two-percentage-point increase alone cannot predict a specific price change.
What is the difference between housing demand and actual home sales?
Housing demand includes households seeking accommodation or wishing to purchase property, while completed sales measure transactions that actually occur. A household may need more space but lack sufficient financing to buy. Consequently, substantial underlying housing needs can coexist with weak resale transactions and declining prices.
Can Canada’s national housing shortage coexist with vacant condos?
Yes. National housing supply estimates aggregate requirements across different regions and housing types. Vacant or unsold condos in a particular building may not meet the needs, budgets or location preferences of households seeking accommodation elsewhere. A shortage of suitable homes can therefore coexist with excess availability in certain local property segments.
Should first-time buyers use the national average home price to set their budget?
Not as their primary benchmark. A national average combines transactions from markets with different prices and property types, and changes in the sales mix can influence the figure. Buyers should use their financial capacity and recent local sales of genuinely comparable homes, then include closing expenses, taxes, insurance, maintenance and other recurring costs.
What should renters and buyers watch if Canadian home construction slows?
They should examine the local supply pipeline, including housing starts, completions and available rental or resale inventory. Slower construction may reduce future choices, but the impact depends on household growth, existing vacant units and economic conditions. CMHC supply research provides broader context, while local market and rental data are necessary for decisions about a specific city.